Dr Coskun Tarkocin
Senior Treasury professional · Liquidity, balance sheet and markets · London
I work on how banks manage liquidity and funding, and I teach it to the people who run and supervise them.
Twenty years across risk, markets and Treasury have taught me that better-run banks serve the economy and society better. I want to help shape how bank Treasury evolves in the age of AI.
- Director level in the Global Liquidity team, Group Treasury of a global bank
- Training for central banks and supervisors from around 30 European countries
- Peer-reviewed research on early warning of liquidity stress
- Panels at Risk Live Europe and Risk Evolve
PhD Economics · CFA Charterholder · FRM
The journey, in five chapters →My journey
- 01The engineer
I learned to see a bank as a system
I trained as an industrial engineer before I studied economics. I still look at a bank the way an engineer looks at a system: what goes in, what comes out, and what breaks first under strain.
- BSc Industrial Engineering
- MA Economics
- 02Inside the bank
From risk management to Group Treasury
I started in credit and market risk, then moved through Markets Finance, product control and liquidity risk management. Each move showed me the same decisions from a different side. I joined Group Treasury in 2020, and since 2022 I have worked at director level in the Global Liquidity team, where I have played a lead part in three of the Group's strategic Treasury programmes: the internal liquidity model, global liquidity optimisation and liquidity transfer pricing.
- Entity, regional and global roles
- Teams across London, Mexico and India
- Leading Businesses and Functions, London Business School
- 03Asking why
Can a bank see liquidity stress coming?
Practice kept raising questions I wanted to answer properly, so I went back to research alongside the day job. I defended my PhD in August 2023, and that October the paper at its heart, applying machine learning to early warning of liquidity stress, was published online in The North American Journal of Economics and Finance.
- PhD Economics, August 2023
- Three peer-reviewed papers, 2023–24
- Former Visiting Research Fellow, King's Business School, 2022–2024
- 04Teaching what I practise
The people who supervise banks
Twice a year, once online and each autumn in person at the Banque centrale du Luxembourg, I present on liquidity management to central banks and supervisors from around 30 European countries, through the European Supervisor Education initiative (ESE). Inside the bank I have trained thousands of bankers in liquidity, risk and Funds Transfer Pricing, and I give guest lectures at King's College London.
- Banque centrale du Luxembourg, every autumn
- King's College London guest lectures, 2024 and 2025
- Panels at Risk Live Europe, Risk Evolve and LiquidityEU
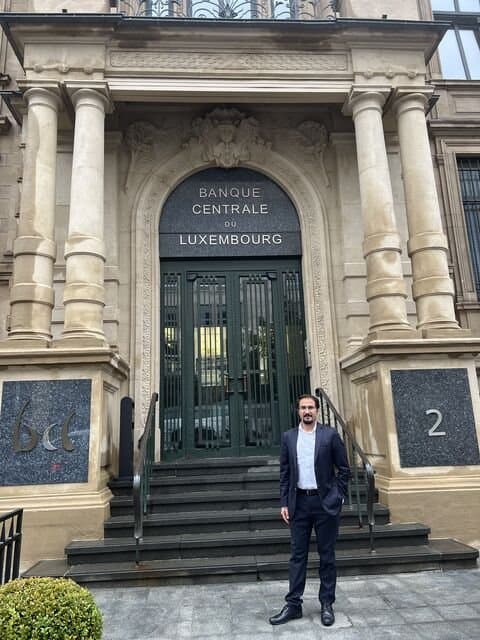
Banque centrale du Luxembourg, October 2024, presenting on liquidity and funding management to European supervisors. - 05What drives me
Better-managed banks serve the economy better
That conviction drives my research and my teaching. My other passion is technology, and learning by doing is my thing.
How I think about liquidity
- 01Design buffers for the first week of stress, not just the 30-day metrics.
- 02A buffer is only usable if it is ready to be monetised, and that readiness is tested.
- 03Speed of access and execution now matter as much as headline buffer size.
- 04Stress events are compressing into days, not weeks or months.
- 05Internal liquidity models matter, because they capture risks the standard metrics miss, such as funding concentration.
- 06Used well, liquidity Funds Transfer Pricing reveals the true cost of liquidity and funding, and leads to better pricing decisions.
Recently
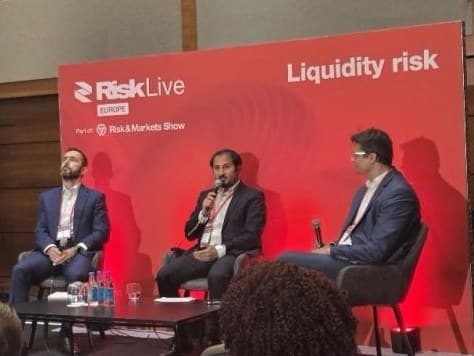
Liquidity buffers at Risk Live Europe
A panel at Risk Live Europe 2026 in London, organised by Risk.net, on designing and calibrating liquidity buffers.
ILAAP training for Europe's supervisors
Training on ILAAP for European central banks and supervisors, which I give twice a year: once online and once in person at the Banque centrale du Luxembourg.
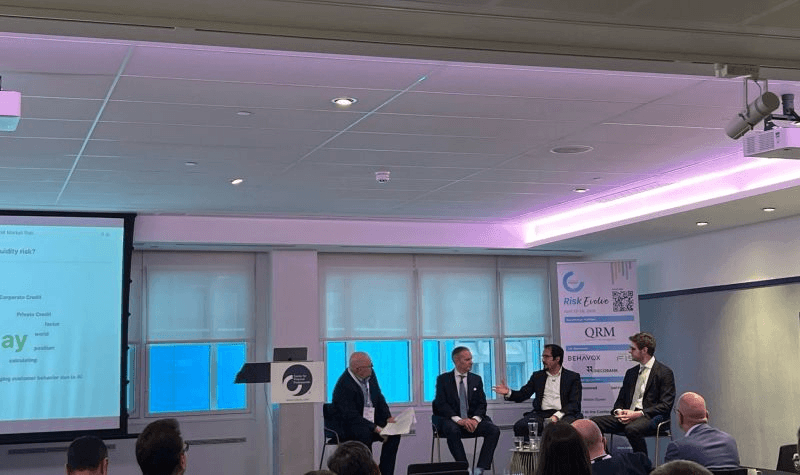
On the panel at Risk Evolve
A panel on liquidity management in volatile market conditions at the Risk Evolve 2026 conference.
Selected publications
- Constructing early warning indicators for banks using machine learning modelsThe North American Journal of Economics and Finance, vol. 69 · 2024 · Coskun Tarkocin and Murat Donduran
- Liquidity classification of equities under stress using machine learning models: evidence from major world share indicesReview of Economics and Finance, vol. 21, pp. 1317–1331 · 2023 · Coskun Tarkocin and Murat Donduran
- Bank stability and systemic risk measurement: application of Z-score variations to the Turkish banking sectorInternational Journal of Finance & Banking Studies, vol. 12, no. 1, pp. 63–73 · 2023 · Coskun Tarkocin and Murat Donduran